
-
File Your Taxes
 Find a Location
File Your Taxes
-
Resolve Tax Issues
Resolve Tax Issues
Resolve Tax Issues
-
Tax Resources
See all Tax Help
Tax Tools
Tax Tips & Resources
-
 Log in | Sign up
JH Accounts


|
Oh no! We may not fully support the browser or device software you are using ! To experience our site in the best way possible, please update your browser or device software, or move over to another browser. |
Get up to $1,500 in minutes! Starting Dec. 10, come in for our Money Today Guarantee, if approved on a prepaid card. Terms apply.
Employment tax tips
Whether you're a small business owner, a freelancer, or a full-time employee, there's a lot you need to know about how your professional status affects your tax situation.
Employment income and work situations
Tax Tips for Day Traders
More and more people are getting involved with day trading. Win or lose, you’ll need to report your activities on your taxes, and pay taxes on the money you make. The good news is, you’re generally taxed less than your regular income, and as a day trader, you could have added tax benefits. Continue reading to find out more about how day trading will affect your taxes, what capital gains tax is, how to qualify for day trader status, what the wash sale rule is, and beyond.
Passive Income: How is Passive Income Taxed?
With high inflation and rising prices, passive income may appear to be a good way to earn some extra cash flow and supplement regular earnings from your day job. But there are rules and considerations to take into account beforehand. Continue reading to find out about passive income tax, what passive income is versus active income, passive income tax deductions, and more.
Tax Tips for Military Families in 2026
There are special tax breaks that members of the United States Armed Forces, their spouses, and veterans should know before filing an income tax return. Understanding these rules and watching this video could help you or someone you love to get a bigger tax refund or understand how to file an accurate income tax return.
Job loss, severance and unemployment
How unemployment can affect your tax return
We know how difficult unemployment can be. Here’s what you need to know before filing your taxes this year.
Lost your job? Here’s how it can affect your taxes
Losing your job comes with a lot of questions about your taxes. Here's what you need to know about unemployment benefits, severance pay, tax credits, and more.
What you need to know about reporting unemployment benefits
“Unemployment benefits” are financial assistance provided by federal and state governments to people who’ve been laid off from their jobs or are out of work. You most likely will have to pay taxes on that income. But not to worry, we’re here to help you understand how to report this income on your tax return. Keep reading to learn more.
Severance pay: How losing a job impacts your taxes
Companies laid off over 1.17 million U.S. workers in 2025. Nearly 500,000 layoffs have occurred in the first half of 2026. If you have been laid off, you definitely don’t want to add IRS surprises to the pain of job loss. Read on to learn how severance pay can affect your taxes.
More Results
Job-specific tax guidance

Tax deductions for artists
If you are an artist, the money you make providing your services may be considered income from self-employment.

Carpenter
If you are a self-employed tradesman or an independent contractor, including a computer technician, electrician, carpenter, construction worker, forklift operator, mechanic, machine operator, painter, plumber, welder, or laborer, you should receive Form 1099-NEC. Payments that you receive for providing trade services, outside of or in addition to your regular job, may be considered income from self-employment and reportable on Schedule C, Profit or Loss from Business. You may deduct all associated expenses to your self-employment income on your Schedule C. Any expenses you have from your W-2 job are not deductible.
A Guide to Self-Employment Tax & Deductions for Clergy and Ministers
If you are a member of the clergy, you should receive a Form W-2, Wage and Tax Statement, from your employer reporting your salary and any housing allowance. Generally, there are no income or Social Security and Medicare taxes withheld on this income. Honoraria and fees that you receive from individuals for marriages, baptisms, funerals, masses, etc., are usually considered income from self-employment and are reportable on Schedule C, Profit or Loss from Business.

Driver
If you are a self-employed driver, whether you drive a yellow cab, Uber, Via, or Lyft, you must report your income on Schedule C. You may receive Form 1099-NEC, Non-Employee Compensation or Form 1099-K reporting income to be reported on your Schedule C. Any income not reported on a 1099, must be included on your Schedule C also. This includes any cash fares and tips you receive while driving. You may deduct all associated expenses to your self-employment income on your Schedule C.

Electrician
If you are a self-employed tradesman or an independent contractor, like an electrician, you should receive Form 1099-NEC. Payments that you receive for providing trade services, outside of or in addition to your regular job, may be considered income from self-employment and reportable on Schedule C, Profit or Loss from Business. You may deduct all associated expenses to your self-employment income on your Schedule C.

Hairstylist
As a hairstylist, if you rent space in a salon, work from home, or travel to your clients, you may be considered self-employed. Self-employed taxpayers report all of their income, including tips, on Schedule C, Profit or Loss from Business. You may deduct all associated expenses to your self-employment income on your Schedule C.

Mechanic
If you are a tradesman, such as a mechanic, machinist, machine operator, welder, or laborer, you should receive Form W-2, Wage and Tax Statement, from your employer. Payments that you receive for providing trade services, outside of or in addition to your regular job, may be considered income from self-employment and reportable on Schedule C, Profit or Loss from Business. You may deduct all associated expenses to your self-employment income on your Schedule C. Any expenses you have from your W-2 job are not deductible.

Nurses and Tax Deductions
Updated on May 3, 2023 If you are a nurse, midwife, or other healthcare worker, you should receive a Form W-2, Wage, and Tax Statement, from the organization employing you. There are no longer deductions available for you as an employee. If you work as a contract nurse, such as a traveling nurse, home health care, etc. you are generally considered self-employed and should receive a Form 1099-MISC, Miscellaneous Income. This income should be reported on Schedule C and you can deduct your expenses related to your work such as mileage driven for your work, supplies, licensing renewal, office expenses, etc.

Tax deductions for performance artists
If you are a performing artist, such as an actor, dancer or musician, payments that you receive from someone who is not your employer (for example, payments for freelance work) may be considered income from self-employment and reportable on Schedule C, Profit or Loss from Business. You may deduct all associated expenses to your self-employment income on your Schedule C. Any expenses you have from your W-2 job are not deductible.

Tax deductions for plumbers
If you are a tradesman, like a plumber, welder or laborer, payments that you receive for providing trade services, outside of or as part of your regular business, may be considered income from self-employment and reportable on Schedule C, Profit or Loss from Business. You may deduct all associated expenses to your self-employment income on your Schedule C. Any expenses you have from your W-2 job are not deductible.
Taxes for Restaurant Workers - Jackson Hewitt
If you are a food or beverage service employee, you should receive Form W-2, Wage and Tax Statement, from your employer. A food or beverage service employee may be a bartender, cook, kitchen helper, waitress/waiter, busboy, maitre d', hostess, dining room captain or wine steward. There are no longer any work deductions available for employees including those in the food services industry.
Tax deductions for salespeople
If you work as a salesperson or sales representative, and you received a Form W-2 and the "Statutory employee" check box is marked in Box 13, report that income on Schedule C, Profit and Loss from Business. You may deduct your business expenses to reduce your overall taxes.

Tax deductions for security specialists
If you work in security or asset protection or as a correctional officer, the money you make providing security services may be considered income from self-employment.

Tax deductions for tradesmen
If you are a self-employed tradesman or independent contractor, like a computer technician, electrician, carpenter, construction worker, forklift operator, mechanic, machine operator, painter, plumber, welder, or laborer, payments that you receive for providing trade services, outside of or as your regular job, may be considered income from self-employment and reportable on Schedule C, Profit or Loss from Business. You may deduct all associated expenses to your self-employment income on your Schedule C. Any expenses you have from your W-2 job are not deductible.

Tax deductions for truck drivers
If you are a driver, such as a bus driver, taxicab driver, or truck driver, you should have received a Form W-2 for your job and none of your job-related expenses are deductible. If you are self-employed you should receive a Form 1099-MISC, Miscellaneous Income and you should report that income, and any expenses, on Schedule C, Profit and Loss from Business.

Tax deductions for welders
If you are a tradesman, like a welder or laborer, payments that you receive for providing trade services, outside of or in addition to your regular job, may be considered income from self-employment and reportable on Schedule C, Profit or Loss from Business.
More Results
Pay, withholding and multiple jobs
Bonus Tax Rate 2026: How Are Bonuses Taxed?
Millions of Americans receive bonuses at work. If you’re one of these millions, here is a guide to what a bonus is, how it’s taxed, and how you may be able to ease your tax burdens on supplemental income and bonuses you may earn when you file your taxes in 2026.
Federal and state withholdings for payroll taxes
Starting a new job and going through other major life events often means that you’ll have to think about making changes to your federal and state withholdings. Withholdings are the amount of local, state, and federal taxes taken out of your paycheck. Read on to learn when you may need to revise your elections, and how paying the right amount in taxes as you go could be the difference between a tax refund or a tax bill when you file your federal and state returns.
No tax on overtime: How does it work?
Need to know how overtime pay affects your taxes? This guide will explain the basics of overtime tax, clear up common misconceptions about higher tax rates on overtime, and give a rundown on how to calculate overtime taxes.
Side hustle tax 2026: Do I have to pay taxes on a side hustle?
More Americans are relying on side-gig earnings. And if you’ve never had a side hustle or second job before, understanding how this income factors into your taxes can be confusing. As a part of our Deductions@Work® series, here’s everything you need to know about how a second job or side gig affects your taxes.

What is FICA Tax? | How FICA Tax Works in 2025
If you have a job, you are almost guaranteed to be paying FICA taxes. They might even take a big bite out of your paycheck. But what exactly are FICA taxes and how do they affect your income? Read on to find out.

Withholding: What is it, and how does it work
Starting a new job and going through other major life events often mean that you’ll have to think about filling out or revising your withholdings. Read on to learn how paying the right amount in taxes as you go could be the difference between a tax refund or a tax bill when you file your federal and state returns.
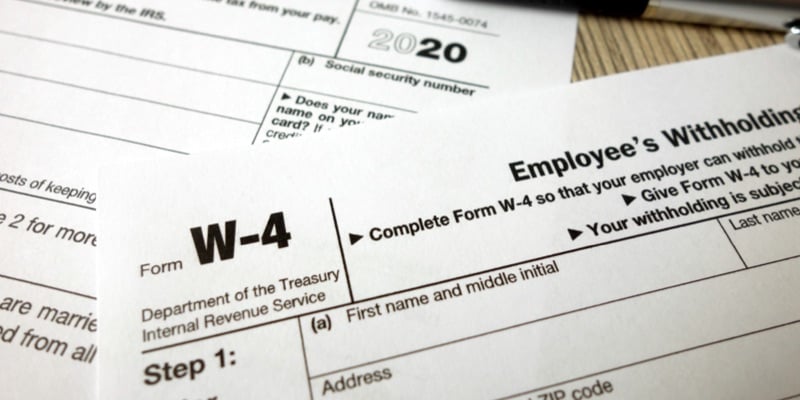
When should I adjust my W-4 withholdings?
It's important to understand how your W-4 withholdings impact your monthly finances and the amount of taxes you owe when you file. In this article, we’ll cover what withholdings are, why it’s important to revisit your withholdings at least once a year, and life changes that should prompt an adjustment to your withholdings using IRS Form W-4.
More Results
Because trust, guarantees, convenience & money all matter
Get your biggest tax refund & much more!
Sign up and be one of the first to access our exclusive promotions and get tax tips that will maximize your money.
We'll only send you the best deals and helpful tips, and we'll never share your email with others. See our Privacy Policy and Terms of Service for more information.
Almost done!
Enter your mobile phone number to get exclusive savings on trusted tax prep, IRS deadline reminders, and more.
We’ll only text you with deals and tax tips to maximize your money. You
can opt out at any time.
By providing your phone number and clicking “Submit,” you agree to receive recurring
marketing and informational calls and texts (including those made using an automatic
telephone dialing system or prerecorded voice) from Jackson Hewitt at the number you
provided. Consent is not a condition of purchase. Message and data rates may apply. Text
STOP to opt out. See our Privacy Policy and Terms of Service for more information.
Thanks for subscribing!
Ready to meet a Tax Pro and maximize your refund money? Book an appointment now.
Your nearest locations
The Money Today Guarantee is only available to clients who (i) are approved for an Early Tax Refund Advance loan; and (ii) elect and are eligible to receive loan funds on a prepaid card. Loan available during hours of operation. Hours vary by location. Loan application must be submitted by 11pm local time. If funds are not credited to your card before 12am local time, Jackson Hewitt will credit $50 within 2 weeks to your card if available or provide you a $50 eGift card. Fees, terms, and conditions apply to the prepaid card.
The Early Tax Refund Advance (ETRA) is a loan secured by, and paid back with, your tax refund and is offered by First Century Bank, N.A. Loan amounts are determined by your expected federal refund, less authorized fees and underwriting. Loan amounts are $300, $500, $1,000, and $1,500. To be eligible for the $1,500 ETRA loan, your expected federal refund, less authorized fees, must be at least $5,000. Most common ETRA loan amount approved is $300. ETRA loan is subject to underwriting and approval. Loan proceeds are typically available on the same day of approval, if disbursed on a prepaid card offered at Jackson Hewitt offices, or in 1-5 business days with direct deposit. Terms and restrictions apply. For details visit jacksonhewitt.com/loans. Jackson Hewitt is a Rhode Island Licensed Loan Broker and holds other relevant licenses for the locations where this product is offered. If approved, a finance charge applies except for residents of CT and NE.
Money Today Guarantee
The Money Today Guarantee is only available to clients who (i) are approved for a refund advance loan; and (ii) elect and are eligible to receive loan funds on a prepaid card. Loan available during hours of operation. Hours vary by location. Loan application must be submitted by 11pm local time. If funds are not credited to your card before 12am local time, Jackson Hewitt will credit $50 within 2 weeks to your card if available or provide you a $50 eGift card. Fees, terms, and conditions apply to the prepaid card.
Early Tax Refund Advance
The Early Tax Refund Advance (ETRA) is a loan secured by, and paid back with, your tax refund and is offered by First Century Bank, N.A. Loan amounts are determined by your expected federal refund, less authorized fees and underwriting. Loan amounts are $300, $500, $1,000, and $1,500. To be eligible for the $1,500 ETRA loan, your expected federal refund, less authorized fees, must be at least $5,000. Most common ETRA loan amount approved is $300. ETRA loan is subject to underwriting and approval. Loan proceeds are typically available on the same day of approval, if disbursed on a prepaid card offered at Jackson Hewitt offices, or in 1-5 business days with direct deposit. Terms and restrictions apply. For details visit jacksonhewitt.com/loans. Jackson Hewitt is a Rhode Island Licensed Loan Broker and holds other relevant licenses for the locations where this product is offered. If approved, a finance charge applies except for residents of CT and NE.