
-
File Your Taxes
 Find a Location
File Your Taxes
-
Resolve Tax Issues
Resolve Tax Issues
Resolve Tax Issues
-
Tax Resources
See all Tax Help
Tax Tools
Tax Tips & Resources
-
 Log in | Sign up
JH Accounts


|
Oh no! We may not fully support the browser or device software you are using ! To experience our site in the best way possible, please update your browser or device software, or move over to another browser. |
IRS TAX PROBLEMS? Get expert help with back taxes, IRS notices, penalties, and more.
IRS Notices: Tax Debt
What is a CP14 notice?
Updated on: June 04, 2024


Getting any notice from the IRS can cause confusion and stress. It’s good that a CP14 notice is intended to be more informational, and less scary, for taxpayers just like you. So, don’t panic, and allow us to better explain what these unfamiliar tax terms are, and how it can affect your taxes. Keep reading to understand what your CP14 notice means.
What is an IRS CP14 notice?
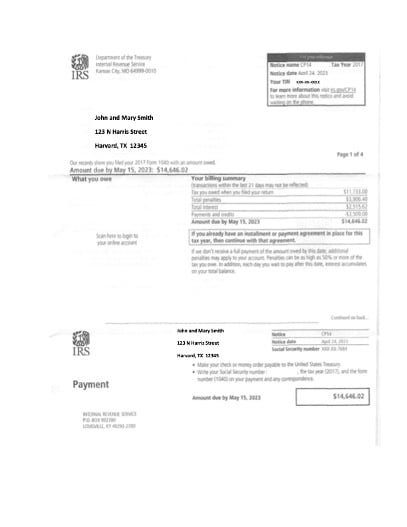
The IRS refers to this as a notice of Tax Due and Demand for Payment. This is the most-common notice sent to taxpayers, and it’s a formal letter letting you, the taxpayer, know that you owe the IRS $5 or more. The CP14 notice will state the amount owed, including interest and penalties, and will request the amount be paid in 21 days (three weeks).
Why did you receive an IRS CP14 notice?
Simply put, you received this notice because you owe taxes to the IRS. Always read a notice from the IRS in full.
Responding to the CP14 notice
Read the notice in full to gather as many details as possible. And if the CP14 notice is too confusing, we’re here for you. Your local Tax Pro can explain the notice and help you determine the best next steps to take.
If you can’t pay in full by the 21-day deadline, you have options, and just knowing that is a great start. The IRS offers payment plan options. If you need assistance, you can speak to a Tax Pro who can review your notice and help determine if you qualify for an IRS program, and help you set up your payment plan.
Payment options
A payment plan is an agreement with the IRS to pay the taxes you owe in an extended timeframe. The IRS offers four options.
- Pay Now
- Pay the tax amount owed in full today. Pay directly from a checking or savings account online, by phone, or in-person. Or pay by check, money order, or credit card (processing fees apply when paying with a credit card). There’s no setup fee to use this type of payment and no future penalties or interest, since you’re choosing to pay now and not later.
- Short-term Payment Plan
- Pay the tax amount owed in 180 days (about six months) or less. You can use the same methods of payment as Pay Now. There’s no setup fee to apply for this plan. Interest and penalties will continue to accrue until you pay the amount in full. If you don’t pay in full within the 180 days (about 6 months), you will be assessed the fee to set up a long-term payment plan.
- Long-term Payment Plan (installment agreement)
- Pay the amount owed in monthly installments. If you’re approved for this plan, you have two options to make payments.
- Direct Debit. This makes automatic monthly payments from your checking account, also known as Direct Debit Installment Agreement (DDIA).
- Monthly payments. With this option, you can make a monthly payment using your checking or savings accounts, money order, or credit/debit card (processing fees apply when paying by card). The setup fees range, depending on how you apply for this plan (online, phone, or in-person) and whether your income is low enough to have the fee waived. Interest and penalties will continue to accrue until you pay the amount owed is paid in full.
- Pay the amount owed in monthly installments. If you’re approved for this plan, you have two options to make payments.
- Change an Existing Payment Plan
- If you’re approved for one of the three plans outlined above, but want to switch to another, you can apply to a different plan, but there are setup fees. There are setup fees if you apply online, or by phone, mail, or in-person. If your income is low enough, there’s a small setup fee to apply by either of these same methods. In some cases, you could get your setup fee back if you qualify. Your local Tax Pro can help you understand if your income qualifies for “low” or not, and whether you meet the criteria.
Penalties and interest
Penalties and interest could add up if you do not pay taxes owed to the IRS on time. The IRS charges a late payment on unpaid taxes. This is usually a 0.5% interest charge on your unpaid balance each month, until you pay your tax bill in full.
It’s best to call the IRS phone number listed on your CP14 notice to make payment arrangements or pay in full. Alternatively, set up a payment plan and payment method online. Finally, you can also pay in full by mail with a check or money order. It is important to act before your 21-day deadline.
What if the IRS says you owe but you already paid?
If you’re able to call the number listed on your CP14 notice, you should do so as soon as possible. Grab your tax documents and paperwork (canceled checks or proof of tax payment, filed or amended tax return, etc.) and have these resources handy.
If calling the IRS doesn’t lead to the solution you were hoping for, speak with one of our Tax Pros. For all other tax-filing needs, we’re in your neighborhood and open all year to help you file your tax return or assist with any tax problem you’re facing.
CP14 notice example
About the Author
Jo Willetts, Director of Tax Resources at Jackson Hewitt, has more than 35 years of experience in the tax industry. As an Enrolled Agent, Jo has attained the highest level of certification for a tax professional. She began her career at Jackson Hewitt as a Tax Pro, working her way up to General Manager of a franchise store. In her current role, Jo provides expert knowledge company-wide to ensure that tax information distributed through all Jackson Hewitt channels is current and accurate.
 Jackson Hewitt Editorial Policy
Because trust, guarantees, convenience & money all matter
-
TRUSTED GUARANTEES.
Be 100% certain about your money & your taxes, year after year.
-
NATIONAL PRESENCE. LOCAL HEART.
We’re in your neighborhood & inside your favorite Walmart store.
-
45 YEARS. 70+ MILLION RETURNS.
The kind of trusted expertise that comes with a lifetime of experience.
Expert help with IRS tax problems
If you’ve got back taxes, received an IRS notice, are facing penalties or more, our team of experts are here to help with a FREE consult.
Get a free consultation
Give us your info and we’ll give you a quick call to assist.
We’re so glad you’re interested!
The Tax Resolution team will give you a call as soon as your request is reviewed.
The Money Today Guarantee is only available to clients who (i) are approved for an Early Tax Refund Advance loan; and (ii) elect and are eligible to receive loan funds on a prepaid card. Loan available during hours of operation. Hours vary by location. Loan application must be submitted by 11pm local time. If funds are not credited to your card before 12am local time, Jackson Hewitt will credit $50 within 2 weeks to your card if available or provide you a $50 eGift card. Fees, terms, and conditions apply to the prepaid card.
The Early Tax Refund Advance (ETRA) is a loan secured by, and paid back with, your tax refund and is offered by First Century Bank, N.A. Loan amounts are determined by your expected federal refund, less authorized fees and underwriting. Loan amounts are $300, $500, $1,000, and $1,500. To be eligible for the $1,500 ETRA loan, your expected federal refund, less authorized fees, must be at least $5,000. Most common ETRA loan amount approved is $300. ETRA loan is subject to underwriting and approval. Loan proceeds are typically available on the same day of approval, if disbursed on a prepaid card offered at Jackson Hewitt offices, or in 1-5 business days with direct deposit. Terms and restrictions apply. For details visit jacksonhewitt.com/loans. Jackson Hewitt is a Rhode Island Licensed Loan Broker and holds other relevant licenses for the locations where this product is offered. If approved, a finance charge applies except for residents of CT and NE.
Money Today Guarantee
The Money Today Guarantee is only available to clients who (i) are approved for a refund advance loan; and (ii) elect and are eligible to receive loan funds on a prepaid card. Loan available during hours of operation. Hours vary by location. Loan application must be submitted by 11pm local time. If funds are not credited to your card before 12am local time, Jackson Hewitt will credit $50 within 2 weeks to your card if available or provide you a $50 eGift card. Fees, terms, and conditions apply to the prepaid card.
Early Tax Refund Advance
The Early Tax Refund Advance (ETRA) is a loan secured by, and paid back with, your tax refund and is offered by First Century Bank, N.A. Loan amounts are determined by your expected federal refund, less authorized fees and underwriting. Loan amounts are $300, $500, $1,000, and $1,500. To be eligible for the $1,500 ETRA loan, your expected federal refund, less authorized fees, must be at least $5,000. Most common ETRA loan amount approved is $300. ETRA loan is subject to underwriting and approval. Loan proceeds are typically available on the same day of approval, if disbursed on a prepaid card offered at Jackson Hewitt offices, or in 1-5 business days with direct deposit. Terms and restrictions apply. For details visit jacksonhewitt.com/loans. Jackson Hewitt is a Rhode Island Licensed Loan Broker and holds other relevant licenses for the locations where this product is offered. If approved, a finance charge applies except for residents of CT and NE.